The Iraqi dinar between strong reserves and a crisis of confidence: Will the dollar’s turmoil turn into wider economic pressures?
 The significance of the Central Bank of Iraq’s recent statement lies not only in its reaffirmation of the country’s sufficient foreign currency reserves, but also in its timing and what it reveals about the nature of the pressures facing the Iraqi economy. On September 19, 2026, the Central Bank confirmed its ability to meet the demand for foreign currency to finance foreign trade, settle bank card transactions, and provide dollars to travelers at the official exchange rate.
It attributed the recent rise in the dollar’s price in local markets primarily to speculation, market expectations, and the exploitation of geopolitical tensions in the region. This reassurance comes at a time when the parallel market has witnessed a significant decline in the value of the dinar, with $100 trading at levels approaching 160,000 Iraqi dinars on the unofficial market. This raises a significant economic paradox: if Iraq possesses substantial foreign currency reserves, why is the dollar rising? And why is the market concerned if the Central Bank’s ability to finance foreign trade remains intact, as the bank asserts? DinarExchange Rates
The answer begins with the necessity of distinguishing between a reserve crisis and a crisis of dollar access and market confidence. The central bank’s possession of large dollar reserves does not necessarily mean that all participants in the economy can obtain them with the same speed and at the same cost. The Iraqi exchange market effectively operates through two channels: official channels subject to banking requirements, compliance rules, and foreign trade financing regulations, and a parallel market that meets other forms of dollar demand. Therefore, the widening gap between the official and parallel exchange rates may indicate demand that is not being fully met through official channels, but it may also reflect increased precautionary and speculative demand stemming from expectations that the dollar will become more expensive in the future.
Here, expectations themselves become a powerful economic force. When households and businesses anticipate a rise in the dollar, demand for it increases. This increased demand drives the exchange rate upward, and this very rise then becomes a source of further anxiety and buying. In this way, the market can enter a cycle of fear, demand, speculation, and then more fear. From this perspective, the Central Bank’s statement should not be interpreted merely as a declaration of the size of Iraq’s financial resources, but also as an attempt to manage market expectations and prevent anxiety from morphing into collective economic behavior that would place further pressure on the dinar.
The second challenge, more directly related to the daily lives of Iraqis, is the transmission of exchange rate fluctuations to prices, inflation, and purchasing power. Iraq relies heavily on imports to meet domestic demand. Consequently, importers who cannot obtain dollars at the official rate and are forced to purchase them on the parallel market will incur higher import costs. This additional cost does not remain with the importer but is gradually passed down the supply chain, from wholesalers to retailers, and ultimately to the end consumer.
At this point, the problem becomes far more significant than simply the rising dollar exchange rate displayed on exchange bureaus’ screens. The dinar’s weakness in the parallel market can translate into higher prices for food, clothing, electronics, spare parts, raw materials, and other imported goods. If household income remains stagnant while prices rise, purchasing power erodes even without a nominal decrease in salaries. This is one of the most important channels through which exchange rate pressures are transmitted to the real economy. Rising prices force households to reduce their consumption, while reduced consumption, in turn, slows down business activity. This issue is particularly important because the central bank itself, in its statement, acknowledged the widespread concerns about rising prices and the slowdown in market activity.
But a longer-term analysis places the current situation within a broader structural problem related to the rentier nature of the Iraqi economy and its heavy reliance on both oil and the dollar. Oil accounts for roughly 90% of Iraq’s government budget revenues, according to Reuters, and a significant portion of these revenues flows through the central bank’s accounts at the Federal Reserve Bank of New York. This structure gives Iraq considerable capacity to build up foreign reserves when oil exports and prices are favorable, but it also makes fiscal and monetary stability highly dependent on the continued flow of oil revenues and regular, reliable access to the international financial system.
In August 2026, Reuters reported that Iraq held over $100 billion in reserves in the United States, highlighting the Iraqi economy’s sensitivity to its financial ties with Washington. Therefore, the fundamental economic question is not simply the central bank’s ability to defend monetary stability today, but rather how long the Iraqi economy can maintain this stability if geopolitical shocks persist or if oil revenues and international financial channels come under continued pressure.
From this perspective, the current situation can be viewed through three possible paths, not as inevitable predictions, but as a framework for understanding risks. The first path is that the recent rise in the dollar is primarily due to speculation and temporary anxiety. In this case, a decrease in geopolitical tensions, continued availability of foreign currency, and a restoration of market confidence could lead to a narrowing of the gap between the official and parallel exchange rates.
The second possibility is that this gap will persist for a longer period. In this case, inflationary pressures become more significant, as businesses and traders may increasingly base their pricing on the actual cost of obtaining dollars rather than the official exchange rate. The longer this divergence continues, the greater the likelihood that the parallel market rate will become a factor in pricing decisions within the domestic economy.
The third scenario, the most economically dangerous, could unfold if persistently high demand for the dollar coincides with a prolonged decline in foreign currency inflows. In that case, the problem would no longer be primarily a crisis of expectations or speculation, but could gradually escalate into pressure on foreign reserves, fiscal policy, imports, and overall economic activity.
Therefore, foreign reserves, however large, should not become a substitute for addressing the structural imbalances plaguing the Iraqi economy. While reserves represent an important line of defense, they are not a permanent solution to the budget’s dependence on oil, the market’s reliance on imports, or the persistent gap between official and parallel channels for obtaining foreign currency. As long as reserves are used to absorb shocks without simultaneously expanding the economy’s capacity to generate alternative sources of foreign currency, economic stability will remain contingent on two factors over which Iraq has no complete control: global oil market conditions and the geopolitical environment.
Therefore, the question that should be at the heart of the Iraqi economic debate is not simply: Does the Central Bank have enough dollars today? Its recent statement confirms that it does. The more important question is: Does the Iraqi economy possess the structure to reduce its recurring need to defend the dinar using oil revenues?
Herein lies the deeper challenge. Sustainable monetary stability is not measured solely by the amount of foreign currency held by the central bank, but also depends on the economy’s ability to produce, export, attract investments, and diversify revenue sources, in addition to developing a banking sector capable of directing foreign currency efficiently and transparently towards legitimate economic activity.
Until these structural foundations are strengthened, the movement of the dollar in Iraq will remain more than just an indicator of exchange market conditions. It will continue to be a mirror reflecting the level of confidence in the economy, a measure of its ability to absorb external shocks, and a test of Iraq’s eventual capacity to transform its oil wealth from a tool used to defend short-term stability into a foundation for building a more diversified economy less vulnerable to future crises.
Economic Studies Unit / North America Office,
Link Center for Research and Strategic Studies GlobalEconomy News
Rawabetcenter.com
 On Wednesday, the Prime Minister’s financial and economic advisor, Mazhar Muhammad Salih, revealed the most prominent features and challenges facing Iraq’s 2027 budget, stressing that its final form is not yet clear, pending the approval of the draft law by the Council of Ministers and its referral to the House of Representatives. Financialnews subscription
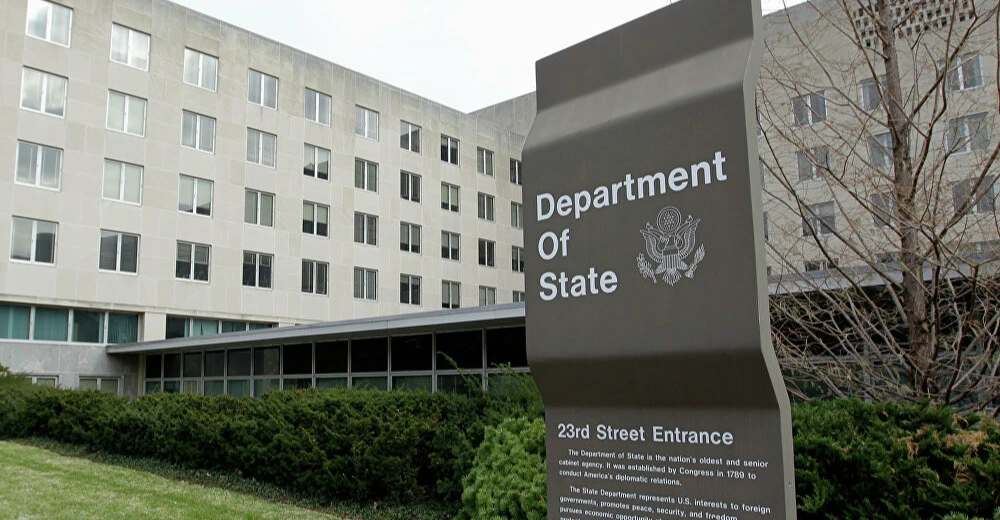 The US State Department affirmed on Wednesday that the United States supports Iraqi Prime Minister Ali al-Zaidi’s efforts to extend state sovereignty and prevent attacks from being carried out inside or launched from Iraq, stressing Washington’s commitment to building a strong and mutually beneficial partnership with Baghdad. Economicnews reports
 The Middle Oil Company reveals its plan to increase production and meet the needs of power plants and refineriesThe Central Oil Company announced on Wednesday the signing of contracts to sell and pump oil through the strategic pipeline and Basra outlets. It also revealed a plan to increase production and meet the needs of stations and refineries in the coming days. The company’s Director General, Muhammad Yassin Hassan, stated in a statement to the official agency that “the Central Oil Company was producing 160,000 barrels per day before the export crisis, with production reaching about 90,000 barrels per day in 2023, and production rising to 160,000 barrels per day in 2025,” stressing that “the crisis of military escalation in the region led to a decrease in oil production.”
 Economic expert Nabil Al-Marsoumi identified five major obstacles facing Iraq’s budget for next year on Wednesday, while warning of a financial deficit that could exceed 60 trillion Iraqi dinars. Financialnews subscription
 A senior US official, speaking to the British newspaper The Independent on Tuesday (September 15), denied any plans to establish “security cooperation with Baghdad” after the scheduled withdrawal date of the 30th of this month.
 Member of the Coordination Framework, Uday Abdul-Hadi, confirmed on Tuesday that the process of voting on nine vacant ministerial portfolios in Ali al-Zidi’s government may extend into October, given the lack of a comprehensive agreement on setting a date for the decisive session in Parliament.
 On Tuesday, MP Abu Turab al-Tamimi revealed the role of Prime Minister Ali al-Zaidi, who “spared” Iraq from almost certain military strikes that were planned for yesterday by Saudi Arabia and the United States. Dailynews subscription
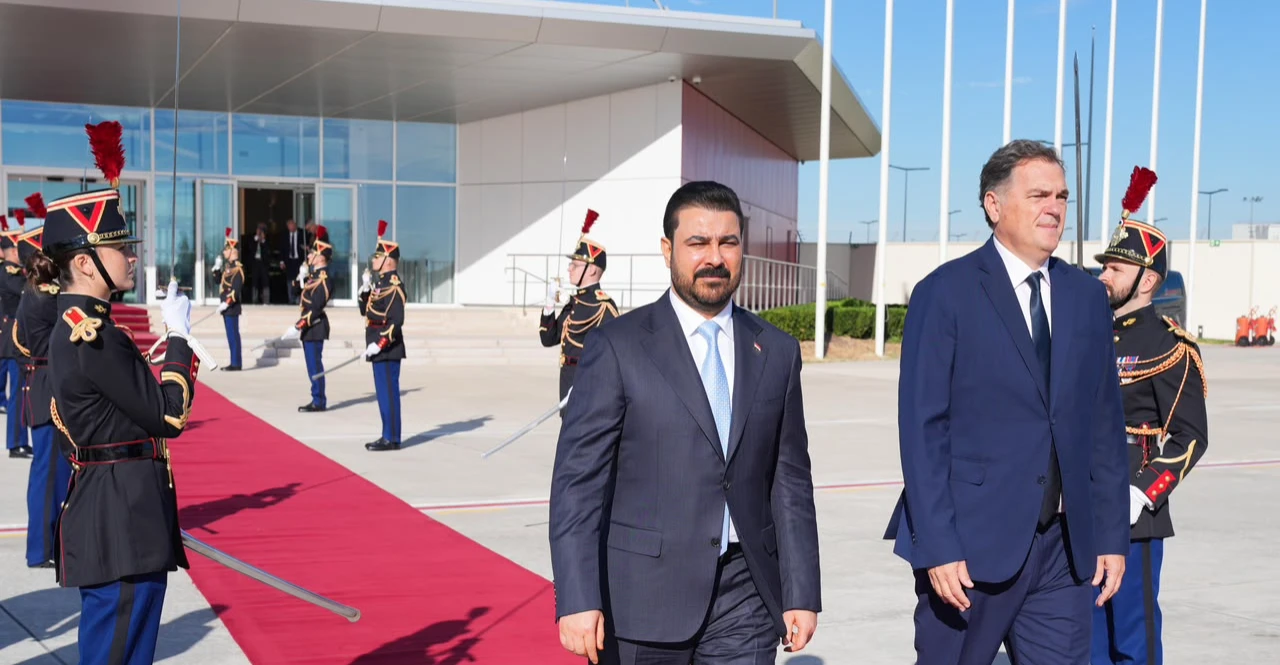 Iraqi Prime Minister Ali al-Zaidi headed to the German capital, Berlin, on Tuesday, after concluding his official visit to France.
 Two deadlines loom for Iraq at the end of September: the end of the decades-long US military presence and the disarmament of pro-Iranian factions, according to a report by the Associated Press. Dailynews subscription